

Credit Sesame: Grow your score

- 32.07K Reviews
- 4.7
- Downloads
- 5,000,000+
Our take on Credit Sesame: Grow your score from Appgk
Managing credit from a phone sounds simple until you need an update at the exact moment a financial decision is in front of you. I found Credit Sesame most useful as a connected finance app: it brings credit monitoring, alerts, and score-building guidance into one mobile place, but its value depends on being able to reach current account information when you need it. That makes it different from a basic budgeting notebook or a static credit reference guide.
Credit Sesame is a free finance app from Credit Sesame, Inc., aimed at people who want a clearer view of their credit without paying for the basic experience. It is rated for Everyone, has built a large audience with over five million installs, and holds a 4.7 average from around 196 thousand ratings. Those figures suggest that it is not a niche tool, although popularity alone does not make every part of the experience right for every user.
I approached it as I would recommend it to a friend: useful for regular awareness, helpful when you want prompts instead of paperwork, and less suitable if you expect a complete replacement for every banking, lending, and identity-protection service you already use. The best results come from treating it as a monitoring and decision-support companion rather than as permission to make credit changes automatically.
How Credit Sesame feels when your connection matters
Network-dependent moments are central to the experience
The app’s main purpose naturally relies on current information. Checking a score, reviewing an alert, or looking at credit-related guidance is more meaningful when the app can connect and refresh what it shows. In my experience, that changes the rhythm of use: I open it when I want an updated view, not merely to browse a collection of permanently stored articles.
Best Parts of Credit Sesame: Grow your score
Things to Keep in Mind About Credit Sesame: Grow your score
This is especially noticeable before a major financial step. Imagine comparing phone plans, preparing to rent an apartment, or considering a new card. I would use the app beforehand to see whether anything looks unexpected and to give myself time to investigate. That is a better workflow than opening it only after an application has already been submitted, because a connection delay or an unresolved account issue is much more stressful when a decision is immediate.
Alerts are another area where connectivity shapes expectations. A notification is useful because it draws attention to something that may deserve a closer look, but I would not treat a phone alert as the only line of defense. I still prefer checking the underlying account or the relevant official source before taking action. The app helps me notice and organize concerns; it should not be the sole authority for a serious financial decision.
News and Features Related to Credit Sesame: Grow your score

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
There is also a practical distinction between an app being available on your phone and the information inside it being ready at all times. A screen may open while a current score, alert, or account-related detail still needs a connection to load. For that reason, I would not plan to use it as my only reference while traveling through areas with unreliable service. I would check important details in advance and keep any necessary account numbers or contact information somewhere I can reach them separately.
Mobile use works best in short, deliberate sessions
The phone format suits the way most people actually think about credit. I rarely want to spend an hour studying my financial profile on a small screen. I want to check what changed, understand why it matters, and decide whether I need to do something next. Credit Sesame is strongest in that quick-review role, particularly when an alert gives the session a clear purpose.
Don't want to read the full review?
A realistic everyday routine might look like this: after receiving an alert, I open the app during a lunch break, review the item, and note whether it matches something I recently did. If it does, I avoid unnecessary panic. If it does not, I make a separate plan to verify the activity through the appropriate account or creditor. That small pause is valuable because it turns a notification into a decision process rather than an emotional reaction.
The mobile setting also encourages frequent glances, which can be helpful and distracting at the same time. Regular checks may help me notice a pattern earlier than an occasional desktop visit. On the other hand, repeatedly checking a score can become unproductive if I start reacting to every movement. Credit health is not improved by staring at a number; it improves through consistent financial behavior. I would use the app to support a routine, not to create a new source of anxiety.
Screenshots
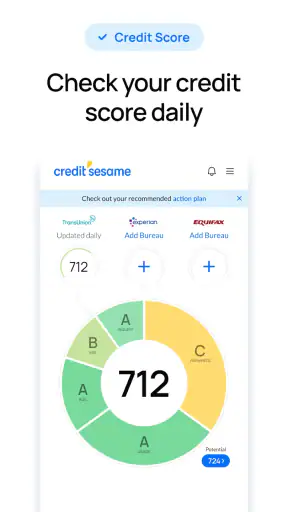
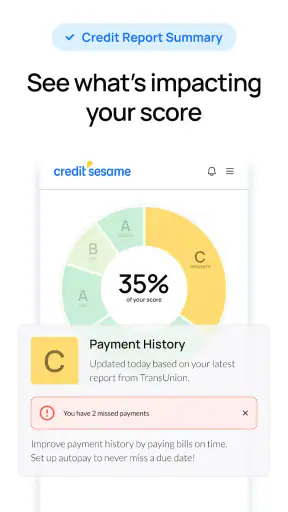
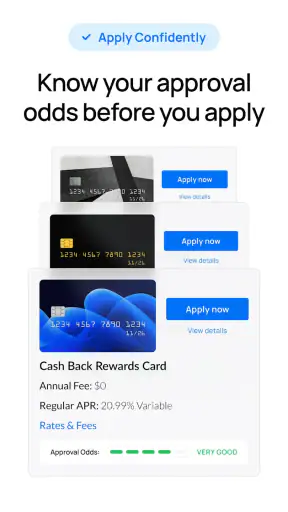
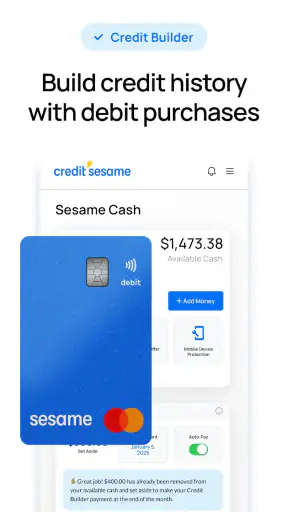
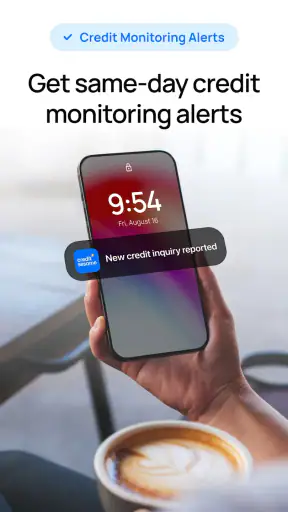
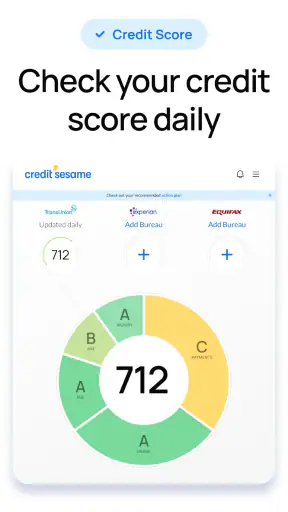
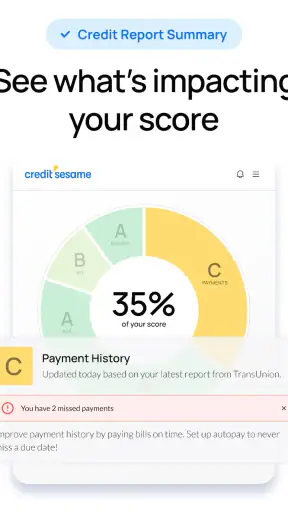
Navigation matters here. Finance apps can become confusing when they mix scores, alerts, recommendations, and educational material. I found the concept of having these areas together convenient, but the convenience also means I need to slow down and distinguish an informative suggestion from an action I am actually ready to take. On a small display, headings and prompts can feel more urgent than they really are, so I read the surrounding explanation before tapping forward.
For someone who manages money mainly from a phone, this is a sensible fit. For someone who prefers printed statements, desktop spreadsheets, or direct conversations with a bank, the app may feel like an additional layer rather than a replacement. I would especially recommend it to a person who knows credit matters but has trouble remembering to check it. I would be more cautious about recommending it to someone who already has a detailed monitoring system and dislikes receiving extra financial notifications.
What happens when a refresh fails
Connectivity problems are not just an inconvenience in a finance app. A delayed refresh can leave me unsure whether I am looking at a current update or an older view. When that happens, the safest response is not to guess. I would retry when the connection is stable, avoid making a major decision based on an incomplete screen, and verify important information through the relevant financial institution.
This is one of the app’s key trade-offs. A connected service can bring timely awareness to a phone, but it also introduces dependence on network availability and successful data retrieval. A paper statement does not suddenly fail to open because reception is poor, although it is less convenient and may not reflect a recent change. Credit Sesame is more immediate when everything connects properly, while traditional records remain useful as a backup for exact account details and historical checking.
If an alert looks unfamiliar, I would use a simple recovery workflow. First, I would confirm that the app has finished loading and that I am not reacting to a partial view. Next, I would compare the information with my own recent activity. Finally, I would contact the appropriate creditor or financial institution through a trusted route if the item still does not make sense. The important insight is that the app can shorten the time between noticing a problem and investigating it, but it cannot remove the investigation itself.
The same caution applies when preparing for an application. I would not open the app in a poor-signal location and assume the first visible screen is the final word. Instead, I would review my information earlier, while I have a reliable connection and enough time to follow up. That simple habit makes the service feel much more dependable because I am not asking it to solve an urgent problem under rushed conditions.
Recovery is also about expectations. If a person wants a tool that performs a complete financial review without any connection, this is probably not the right choice. The app’s purpose is tied to connected monitoring and current guidance, so its strengths appear when it can communicate with its service. Someone who frequently works offline should keep a separate method for recording debts, payment dates, and contact details rather than relying on a mobile finance app alone.
Using the app without losing control of your information
Finance apps deserve a more careful approach than entertainment apps because the subject matter is personal. I would install Credit Sesame only on a device protected with a strong screen lock, keep the operating system current, and avoid reviewing sensitive details on a shared phone. I would also be selective about notifications, since a message preview can reveal more than I want displayed on a locked screen.
Staying data-conscious does not mean avoiding the app altogether. It means deciding when a connected check is genuinely useful. For example, I might review an alert over a trusted home connection rather than opening detailed financial information on public wireless service. If I am using mobile data, I would keep sessions focused instead of repeatedly refreshing out of curiosity. The practical benefit is less exposure and a calmer habit.
I also pay attention to the difference between monitoring and taking action. A recommendation inside a credit app may be relevant, but I do not accept every offer or follow every suggested path automatically. I compare the suggestion with my own goals, existing accounts, and ability to manage another payment. This is a particularly important trade-off for newcomers: guidance can make credit feel less mysterious, but convenience can also encourage decisions that deserve more time.
One useful habit is to write down why I opened the app before I begin. If the purpose is to investigate an alert, I focus on that alert. If the purpose is to understand my current position before a planned application, I review the relevant information and stop. This prevents a short monitoring session from turning into aimless browsing through financial prompts.
Another is to separate app information from official records. I use Credit Sesame to notice changes and build awareness, then use the creditor, lender, or account provider for confirmation when accuracy matters. That two-step approach is more reliable than treating one mobile dashboard as a universal financial record. It also helps me understand what the app is genuinely good at: bringing attention and context together in a place I am likely to check.
Where it beats familiar alternatives, and where it does not
Compared with checking a credit report only when applying for something, Credit Sesame encourages a more regular habit. That can be a real advantage for people who otherwise miss changes until they become urgent. Compared with a budgeting app, its focus is different: a budget helps me plan cash flow and spending, while this app centers on credit awareness and score growth. I would not choose one as a complete substitute for the other.
Compared with going directly to a bank or card issuer, the app offers a broader place to review credit-related information rather than limiting me to one institution. That wider view is convenient when my accounts are spread across providers. The trade-off is that a direct provider remains the better destination for account-specific confirmation, payment actions, disputes, and the most authoritative details about that particular relationship.
Compared with a desktop credit-monitoring service, the phone experience is easier to fit into small moments. I can check an alert while away from my desk and build a habit around brief reviews. A desktop may still be better for people who want to compare documents side by side or keep detailed records while investigating a complicated issue. Credit Sesame is not automatically better; it is better for a mobile-first routine.
The app is also not the right choice for someone seeking individualized financial advice from a person. Educational guidance and prompts can help me ask better questions, but they do not know every detail of my household, obligations, risk tolerance, or long-term plan. If my situation involves serious debt, disputed activity, or a complicated lending decision, I would use the app as an organizing aid and seek the appropriate professional or official support as well.
My verdict on connected credit monitoring
Credit Sesame succeeds because it makes credit something I can revisit in ordinary moments instead of a subject I remember only during an application. Its free price removes an obvious barrier, and the combination of monitoring, alerts, and credit-building guidance gives the app a clear role in a personal finance routine. The current release is version 7.30.1, and it supports operating system version 10 or later, so compatibility is worth checking before installation.
My strongest recommendation is for a person who wants gentle structure: someone who will benefit from seeing alerts, checking progress, and learning what deserves attention without opening several separate services. I would use it before a planned financial decision, after an unexpected notification, and during a regular monthly review. I would not use it as my only record, my only fraud response, or a substitute for a full budget.
The connection requirement is both the reason the app feels useful and the reason I would prepare around it. When the network is available, current-looking information and timely prompts make mobile monitoring practical. When the connection fails, the app cannot replace official records or a backup plan. That is not a deal-breaker for me; it simply defines the correct role.
My final take: this is a worthwhile free finance companion for building awareness and making credit checks easier to remember, provided you verify important details through the proper source and avoid treating every prompt as a command. If you want a connected credit overview that fits short phone sessions, I would recommend trying it. If you need offline records, detailed budgeting, or personalized human advice, pair it with a different tool rather than expecting one app to cover everything.
Credit Sesame: Grow your score FAQ
What is Credit Sesame: Grow your score used for?
Credit Sesame: Grow your score is designed to help users monitor and understand their credit profile. It typically provides access to credit score information, credit report details, alerts, personalized recommendations, and financial education. The app can help you notice changes or possible inaccuracies, but it does not instantly repair credit or guarantee approval for loans, cards, or other financial products.
Is Credit Sesame: Grow your score free to download and use?
The app can generally be downloaded without an upfront charge, and it offers free tools for checking credit-related information and receiving account alerts. However, some features, offers, or partner services may have separate terms, eligibility requirements, or costs. Before accepting a financial product, carefully review interest rates, fees, promotional conditions, and privacy disclosures rather than assuming every service is completely free.
Will using Credit Sesame affect my credit score?
Checking your own credit information through Credit Sesame is generally associated with a soft inquiry, which does not normally lower your credit score. This is different from applying for a credit card, loan, or other product through an offer displayed in the app, because a provider may perform a hard inquiry during the application process. Always read the application terms before submitting personal information.
How accurate and current is the credit information shown in the app?
Credit scores and report information in Credit Sesame are based on data supplied by credit-reporting sources and may not update at the exact moment a lender changes your account. Different lenders report on different schedules, and the score shown may use a model that differs from the one used by a bank or creditor. If something looks incorrect, compare official reports and contact the relevant bureau or lender.
Is Credit Sesame safe for entering personal and financial information?
Credit Sesame requires sensitive information to provide personalized credit tools, so users should review its privacy policy, security practices, permissions, and account settings before registering. Use a unique password, enable available security protections, and avoid accessing the account on unsecured public networks. The app can help organize credit information, but you should remain cautious about scams, unsolicited messages, and financial offers.











